Collateral Assignment of Life Insurance: How It Works

A collateral assignment of life insurance allows a policy owner to use a life insurance policy as security for a loan. Instead of transferring full ownership of the policy to the lender, the lender is given a limited financial interest in the policy while the debt remains outstanding.

If the insured dies before the loan is repaid, the lender may receive the amount it is entitled to under the collateral assignment, generally up to the outstanding debt. Any remaining death benefit is then available to the policy’s beneficiaries, subject to the policy terms and assignment agreement.

Collateral assignments are commonly associated with business financing and may be requested when a lender wants life insurance to help secure a loan.

Key Takeaways

  • A collateral assignment uses a life insurance policy as security for a debt.
  • The lender is generally the assignee, not the policy’s beneficiary.
  • The policy owner normally continues to own the life insurance policy.
  • The lender’s interest is generally limited by the debt and the terms of the assignment.
  • Beneficiaries may receive the remaining death benefit after the lender’s valid claim is satisfied.
  • Once the loan is repaid, the collateral assignment should be formally released according to the lender’s and insurance company’s procedures.

Example of a Life Insurance Collateral Assignment

Suppose a business owner has a $1 million life insurance policy and uses it as collateral for a business loan.

At the time of the owner’s death:

  • Life insurance death benefit: $1,000,000
  • Outstanding loan balance: $250,000

If the lender is entitled to $250,000 under the collateral assignment, the insurer would generally pay that amount to satisfy the lender’s claim. The remaining $750,000 would then be available to the policy’s beneficiaries, subject to the policy and assignment terms.

If the loan had already been repaid and the collateral assignment properly released before the insured’s death, the lender would no longer have a claim under that assignment.

Why Would a Lender Require Life Insurance as Collateral?

Collateral Assignment vs. Naming a Lender as Beneficiary

A lender may require life insurance as collateral when repayment of a loan depends heavily on a particular person, such as a business owner or key individual. If that person dies before the loan is repaid, the loss could make it difficult for the business or family to continue making payments.

A collateral assignment of life insurance can help reduce that risk. It gives the lender a financial interest in the policy while the loan is outstanding.

If the insured dies before the debt is fully repaid, the lender may receive the amount it is entitled to under the assignment. Any remaining death benefit is generally paid to the policy’s beneficiaries, subject to the policy and assignment terms.

Once the loan has been repaid, the lender’s interest should be formally released with the insurance company.

What Types of Life Insurance Can Be Used as Collateral?

Several types of life insurance may be used for a collateral assignment. The right policy will depend on the lender’s requirements, the length of the loan, the amount of coverage needed, and the insurance company’s rules.

Term Life Insurance

Term life insurance can often be used for collateral assignment and may be an attractive option when coverage is needed for a specific period of time.

For example, if a lender requires life insurance to secure a 10-year business loan, an appropriate term policy may provide the required death benefit during that period.

Term insurance does not normally build cash value, but it can still provide the death-benefit protection a lender is looking for. It is also often less expensive initially than permanent life insurance.

Whole Life Insurance

Whole life insurance can also be used as collateral. Unlike term insurance, whole life is designed to provide permanent coverage and generally accumulates cash value over time.

This may be useful when the policy owner already has a whole life policy or wants coverage that can continue beyond the loan period.

Because whole life policies can have cash value as well as a death benefit, it is especially important to understand exactly what rights the collateral assignment gives the lender.

Universal Life Insurance

Universal life insurance may also be used for a collateral assignment, depending on the policy and lender requirements.

Universal life is a form of permanent life insurance that can provide long-term coverage and may accumulate cash value. However, policy performance and guarantees vary considerably among universal life products.

If universal life insurance is being used to secure a loan, the policy owner should make sure the coverage remains in force and continues to satisfy the lender’s requirements.

Important: Not every lender or insurance company handles collateral assignments in exactly the same way. Before purchasing a policy specifically for a loan, confirm the lender’s requirements and the insurer’s assignment procedures.

A collateral assignment and naming a lender as beneficiary are not the same thing.

With a collateral assignment, the lender is generally given a limited financial interest in the life insurance policy to help secure a debt. The lender is known as the assignee, while the policy owner can generally continue to name personal beneficiaries, subject to the assignment and policy terms.

If the insured dies while money is still owed, the lender may receive the amount it is entitled to under the collateral assignment. The remaining death benefit is generally paid to the policy’s beneficiaries.

For example, suppose you have:

 Collateral Assignment Example
Life insurance death benefit$1,000,000
Amount payable to lender under assignment$200,000
Remaining death benefit$800,000

In this simplified example, the lender could receive $200,000, while the remaining $800,000 would generally be available to the designated beneficiaries, subject to the policy and assignment terms.

Naming a lender directly as a beneficiary works differently because the lender is designated to receive the beneficiary share specified under the policy rather than relying on the limited rights created by a collateral assignment.

For someone using life insurance to secure a loan, this distinction matters. A collateral assignment is designed to protect the lender’s financial interest while preserving the remaining policy proceeds for the beneficiaries when applicable.

Benefits of Collateral Assignment:

    • Access to Capital Without Policy Surrender: This is a major advantage. Policyholders can leverage the cash value of their life insurance policy to obtain a loan without having to surrender the policy, which would terminate coverage and potentially incur surrender charges or taxes.

    • Preservation of Beneficiary Designations: The designated beneficiaries of the life insurance policy remain in place. They will still receive the death benefit, minus any outstanding loan amount claimed by the lender in case of the insured’s death before the loan is repaid.

    • Avoids Direct Policy Loan Limitations/Impacts: While direct policy loans reduce the death benefit immediately, a collateral assignment secures an external loan, keeping the full death benefit intact unless a default occurs.

    • No Credit Checks (for the policy itself): While the external loan itself will have credit checks, the ability to use the policy as collateral isn’t based on your credit score, but on the policy’s cash value.

    • Utilizes a “Sleeping” Asset: Many life insurance policies accumulate significant cash value over time that sits dormant. Collateral assignment allows policyholders to put this asset to work without liquidating it.

    • Business Financing Tool: It’s particularly beneficial for business owners who can use the cash value of personal or key person life insurance policies to secure business loans or lines of credit, thereby avoiding the need to pledge other business assets.

Conclusion:

Collateral assignment of life insurance provides a flexible and powerful way to leverage the value of your policy without giving up ownership or beneficiary rights. It’s a strategic option for those seeking external financing, allowing them to unlock the wealth built within their life insurance coverage. By understanding its mechanics and implications, you can make informed decisions about utilizing this unique financial tool.

Yes. A life insurance policy can often be used as collateral for a loan through a collateral assignment. This gives the lender a financial interest in the policy while the loan is outstanding, without necessarily transferring ownership of the policy to the lender.

If the insured dies before the loan is repaid, the lender may receive the amount it is entitled to under the assignment. Any remaining death benefit is generally available to the policy’s beneficiaries, subject to the terms of the policy and assignment.

Yes. Term life insurance can often be used for a collateral assignment, even though term insurance does not build cash value.

For many borrowers, term life insurance can be a practical option because it provides a death benefit for a specific period of time. The lender will typically want to make sure the amount of coverage and the length of the term meet its loan requirements.

Yes. Whole life insurance can be used as collateral when permitted by the lender and insurance company.

Whole life insurance provides a death benefit and typically builds cash value over time. Because policy provisions and lender requirements can vary, it is important to understand exactly what rights are being assigned before completing a collateral assignment.

Usually, no. With a collateral assignment, the lender generally becomes the assignee rather than the beneficiary.

This is an important distinction. The lender’s interest is generally limited to what it is entitled to receive under the assignment, such as the remaining loan balance. If there are death-benefit proceeds left after the lender’s valid claim is satisfied, they are generally paid to the policy’s designated beneficiaries.


In most cases, the policy owner continues to own the life insurance policy after a collateral assignment.

The lender does, however, receive certain rights under the assignment while the debt remains outstanding. This can affect the owner’s ability to make certain changes to the policy, so it is a good idea to check with both the insurance company and lender before making significant policy changes.


If the insured dies while a collateral assignment is in effect, the lender may receive the amount it is entitled to under the assignment. Any remaining death benefit is generally paid to the policy’s beneficiaries.

For example, suppose the policy has a $500,000 death benefit and $100,000 is payable to the lender under the assignment. The remaining $400,000 would generally be available to the beneficiaries, subject to the policy and assignment terms.

Once the loan has been fully repaid, the lender’s interest in the life insurance policy should be formally released.

This is an important final step. Don’t simply assume that paying off the loan automatically removes the collateral assignment from the insurance company’s records. Ask the lender and insurer what documentation is required and confirm that the release has been properly recorded.

Yes. You may be able to use an existing life insurance policy for a collateral assignment instead of purchasing a new policy.

The lender will usually review whether the existing policy meets its requirements, including the amount of coverage and how long the coverage will remain in force. The insurance company must also permit and properly record the assignment.

Yes. A collateral assignment of life insurance may be used in connection with certain SBA-backed business loans when life insurance is required as part of the lender’s risk protection.

Whether life insurance is required—and how much coverage is needed—depends on the circumstances of the loan and applicable SBA and lender requirements. If your lender requests life insurance, ask for the required coverage amount and assignment instructions before applying for a policy.

The main difference is how much control over the life insurance policy is transferred.

With a collateral assignment, the lender or other assignee receives limited rights in the policy, usually to secure a debt. The policy owner generally keeps ownership, subject to the assignee’s rights.

With an absolute assignment, ownership rights in the policy are transferred to another person or entity.

A simple way to remember it is: collateral assignment provides limited rights for a specific purpose; absolute assignment transfers ownership.

You may be able to change beneficiaries while a life insurance policy is under collateral assignment, but there can be restrictions.

The assignment may give the lender certain rights that affect changes to the policy, and the insurance company may require the lender’s consent for some transactions. Before making a beneficiary change, check with the insurer and lender so you know exactly what is permitted.

A collateral assignment generally remains in place until the debt or other obligation it secures has been satisfied and the assignment is formally released, subject to the terms of the assignment.

Once the loan is paid off, follow up with the lender and insurance company to make sure the release is completed and recorded. Keeping a copy of the release with your policy records is also a good idea.
Share:
Reading time: 11 min
Return of Premium

Return of Premium Term Life Insurance: How It Works


On This Page

What Is Return of Premium Term Life Insurance?

Return of premium term life insurance, often called ROP term life insurance, provides temporary life insurance coverage while giving you an opportunity to receive your premiums back if you outlive the policy term.

Like traditional term life insurance, you select a coverage amount and a term, commonly 20 or 30 years. If you die while the policy is in force, your beneficiaries receive the policy’s death benefit.

The difference comes at the end of the term. If you are still living and have satisfied the policy’s requirements, the insurance company may return the eligible premiums specified by the policy.

The trade-off is simple: return of premium coverage generally costs considerably more than traditional term life insurance. That’s why it is important to compare both options before deciding whether getting your premiums back is worth the additional cost.

Return of Premium at a Glance

Traditional Term LifeReturn of Premium Term
Lower premiumsHigher premiums
Deathe benefit during the termDeath Benefit during the term
Generally no premium refund if you outlive the termEligible premium may be returned if policy requirements are met
Best for maximizing affordable coveragemay appeal to buyers who value the premium-refund feature

How Does Return of Premium Term Life Insurance Work?

Return of premium term life insurance works much like traditional term life insurance, but with one important difference: if you outlive the policy’s specified term and meet the policy requirements, some or all of the eligible premiums you paid may be returned to you.

Here’s the basic process:

  1. Choose your coverage amount.
    You select a death benefit based on your family’s financial needs.
  2. Choose the policy term.
    Available terms vary by insurer. Some ROP policies, for example, offer 20- or 30-year level-premium periods.
  3. Pay the required premiums.
    Your premiums are generally higher than comparable traditional term life insurance because of the return-of-premium feature.
  4. If you die during the covered term, your beneficiaries receive the death benefit.
    The policy functions as life insurance during the term.
  5. If you outlive the term, you may receive eligible premiums back.
    The amount returned and the requirements depend on the specific policy. For example, some policies require all scheduled premiums to have been paid and reduce the refund for outstanding loans or withdrawals.

Simple Example

Suppose you purchase a 20-year return of premium term policy and pay:

$100 per month × 12 months × 20 years = $24,000

If you die during the covered term, the policy’s death benefit would generally be paid to your beneficiaries according to the contract.

If you live through the 20 years and satisfy the policy’s return-of-premium requirements, the policy could return the eligible premiums specified in the contract.

The key idea: You pay more for ROP term life than for traditional term coverage in exchange for the possibility of receiving eligible premiums back if you outlive the specified term and satisfy the policy requirements.

What Premiums Are Actually Returned?

If you outlive the specified term of a return of premium life insurance policy, the insurer may refund some or all of the eligible premiums you paid, subject to the terms of the policy.

For example, some ROP term policies return the scheduled premiums paid during the initial term if the death benefit was not paid and all required premiums were made.

However, the refund may not necessarily include every charge or payment associated with your coverage. Depending on the policy:

  • Rider premiums or additional benefits may be treated differently.
  • Policy loans or withdrawals may reduce the amount returned.
  • Unpaid loan interest may also reduce the refund.
  • A lapse or early cancellation can affect or eliminate the return-of-premium benefit.
  • Fees or other policy charges may not qualify for refund under some contracts.

Simple Example

Suppose your eligible ROP premium is $125 per month for 20 years.

$125 × 12 × 20 = $30,000

If you keep the policy in force for the entire term and satisfy its requirements, the policy could return $30,000 at the end of the term.

But if part of your payment went toward benefits that aren’t refundable—or if the policy had loans, withdrawals or other adjustments—the actual amount returned could be different.

Important

Always review the policy’s return-of-premium provisions before purchasing coverage. The contract determines which premiums qualify for a refund, when the refund is payable, and what circumstances can reduce or eliminate it.

Return of Premium Term Life vs. Regular Term Life

Both policies provide life insurance protection for a specified period. The major difference is what happens if you outlive the term.

With traditional term life insurance, coverage generally ends without a refund of the premiums you’ve paid. With Return of Premium (ROP) term life insurance, eligible premiums may be returned if you outlive the specified term and meet the policy requirements. ROP coverage generally costs more because of this additional feature.

FeatureRegular Term LifeReturn of Premium Term Life
Death benefitYes, if the insured dies while the coverage is in forceYes, if the insured dies while the coverage is in force
Coverage periodFixed termFixed term
Premium costGenerally lowerGenerally higher
Premium refundGenerally none if you outlive the termEligible premiums may be retured
Early cancellationCoverage ends; generally no refundMay reduce or eliminate the ROP benefit depending on the policy
Cash valueGenerally noneRop should not be confused with traditional permanent-policy cash value
Best suited forPeople prioritizing affordable death-benefit protectionPeople willing to pay more for the potential retun of eligible premiums
Looking for lower-cost coverage? Learn about traditional term life insurance.

Which One Costs More?

Return-of-premium term life insurance generally costs significantly more than comparable traditional term coverage. The additional premium pays for the return-of-premium feature.

For example, imagine comparable coverage costs:

Traditional term: $50/month
ROP term: $100/month

Over 20 years:

Traditional term: $12,000 in premiums
ROP term: $24,000 in premiums

The ROP policy could potentially return eligible premiums at the end of the specified term, while traditional term generally would not.

But the ROP policy required an additional $12,000 of cash flow over those 20 years.

That’s why the decision shouldn’t simply be:

“Do I want my premiums back?”

A better question is:

“Is the potential premium refund worth paying substantially more for the coverage?”

How Much Does Return of Premium Term Life Insurance Cost?

Return of premium term life insurance generally costs more than traditional term life insurance because the policy includes the potential return of eligible premiums if you outlive the specified term.

Your actual premium depends on factors such as:

  • Age
  • Health and medical history
  • Coverage amount
  • Length of the policy term
  • Tobacco use
  • Insurance company and underwriting

For example, a traditional term policy might offer the lowest-cost way to obtain a large death benefit, while an ROP policy for the same person and coverage amount could cost substantially more.

The important question isn’t simply “How much does ROP insurance cost?” It’s whether the additional premium is worth the potential refund at the end of the term.

Tip: Compare ROP and traditional term life quotes side by side. You may find that the premium difference makes one option more suitable for your budget and financial goals.

Coverage Amount:$500,000
at Preferred Risk
Length of Term: 30
Return of Premium
Term
[Monthly Cost]
Return of Premium
Term
[Monthly Cost]
AGEMALEFEMALE
35$75.69$59.60
40
$119.63$92.22
45$187.05$139.20
50$312.77$230.12
Premium are subject to change by the insurance company. For current rates, please give us a call at 1.866.526.7264.

Pros and Cons of Return of Premium Term Life Insurance

Return-of-premium term life can be attractive if you like the idea of getting your premiums back, but the additional cost makes it important to compare it with traditional term coverage.

Potential AdvantagesPotential Disadvantages
Provides a death benefit during the termPremium are generally higher than regular term
Eligible premiums may be returned if you outlive the policyThe higher premium leaves less money available for saving or investing
Appeals to people who dislike ‘losing’ premiumsCanceling or allowing the policy to lapse may affect the refund
Encourages maintaining coverage for full termNot every payment, rider or charge is necessarily rufundable
Premium refund is based on policy contractProduct availability and terms vary by insurer

The Bottom Line

ROP term life may make sense if you want temporary life insurance protection and are comfortable paying more for the potential return of eligible premiums. If your priority is obtaining the largest death benefit for the lowest premium, traditional term life may be more appropriate.

The best approach is to compare both options side by side before deciding.

Who Should Consider Return of Premium Term Life Insurance?

ROP term life may be worth considering if you:

  • Want term life protection but like the possibility of receiving eligible premiums back.
  • Can comfortably afford the higher premium compared with traditional term life.
  • Expect to keep the policy for the full term.
  • Prefer a predictable premium-refund feature rather than paying for traditional term coverage with no refund at the end.

If your main goal is getting the most life insurance coverage at the lowest cost, traditional term life may be the better option to compare.

FREQUENTLY ASKED QUESTIONS (FAQ)

Generally, a refund of premiums you paid is not considered taxable income because it is typically treated as a return of your own money. However, tax treatment can depend on individual circumstances, so consult a qualified tax professional when necessary.

ROP term life should not be confused with permanent life insurance cash value. Some policies may provide certain values or features during the term, but these vary by contract.

Availability varies by insurer, age, health, coverage amount and state. Comparing quotes can help you determine whether ROP or traditional term coverage better fits your needs and budget. Just use the quote engine on the top of this page to run your real-time quotes.

If you cancel your ROP life insurance policy before the end of the term, you may not receive a refund of premiums, or receive partially refund based on for how long your policy was active. However, if you outlive the term of the policy, you will receive a refund of all the premiums paid.

If you outlive your term life insurance policy, the coverage will expire and you will not receive a death benefit payout. Some policies may have the option to renew or convert to a permanent life insurance policy.

Generally, a refund of premiums you paid is not considered taxable income because it is typically treated as a return of your own money. However, tax treatment can depend on individual circumstances, so consult a qualified tax professional when necessary.

Share:
Reading time: 7 min
A Couple

Life Settlement: How to Turn Your Life Insurance Policy Into Cash

A life settlement is the sale of an existing life insurance policy to a third-party buyer for a lump-sum cash payment that is greater than the surrender value but less than the death benefit.
In simple terms, it lets policyholders sell their life insurance for immediate money — while the buyer takes over future premiums and receives the death benefit when the insured passes away.

Life settlements are often used by seniors aged 65 or older, or those who no longer need their policy, can’t afford the premiums, or want to access funds for medical, retirement, or long-term care needs.

How a Life Settlement Works

  1. Evaluation of Your Policy:
    A licensed life settlement provider or broker reviews your policy type, face amount, premiums, and health information.

  2. Receiving Offers:
    If your policy qualifies, the broker or provider obtains bids from institutional investors (not individuals).

  3. Accepting an Offer:
    Once you agree to a cash offer, ownership of the policy transfers to the buyer.

  4. Getting Paid:
    You receive a lump-sum payment — typically within weeks — and are released from any future premium obligations.

  5. Buyer Assumes Ownership:
    The new owner becomes the beneficiary and continues paying the premiums.

Example of a Life Settlement

Let’s say John, age 75, owns a $500,000 universal life policy. He no longer needs the coverage because his children are financially independent, and his spouse has passed away.

  • Cash surrender value: $20,000

  • Annual premium: $8,000

  • Life settlement offer: $95,000

By selling his policy, John receives $95,000 cash today — nearly five times the surrender value — and eliminates future premium payments.
This allows him to use the money for healthcare, living expenses, or travel, rather than letting the policy lapse.

Why Consider a Life Settlement?

Types of Life Settlements

Life settlements can make financial sense in several real-life situations:

  • Premiums Are Too Expensive:
    If maintaining your policy strains your budget, selling it removes that burden.

  • No Longer Need Coverage:
    Many seniors buy life insurance to protect family income or pay off mortgages — needs that may fade later in life.

  • Need Cash for Retirement or Healthcare:
    A settlement can help fund medical bills, long-term care, or simply increase monthly income.

  • Policy About to Lapse:
    If you’re considering letting your policy lapse, a life settlement can provide a financial return instead of losing everything.

There are several kinds of settlements depending on the policy type and the seller’s situation:

1. Traditional Life Settlement

For seniors aged 65+ with universal or whole life insurance. The most common form.

2. Viatical Settlement

For those with a serious or terminal illness. Usually offers a higher payout since life expectancy is shorter.

3. Retained Death Benefit

Instead of selling the entire policy, you sell part of it and keep a portion of the death benefit for your beneficiaries.

4. Hybrid Life Settlement

Combines selling the policy with funding a long-term care plan or annuity.

Life Settlement vs. Surrender vs. Lapse

OptionWhat It MeansTypical Outcome
Life SettlementSell your policy to a third partyReceive 4–8× more than surrender value
SurrenderReturn policy to insurerGet small cash value
LapseStop paying premiumsLose all value and coverage

Example:

If your policy has a $25,000 surrender value, a life settlement could bring you $100,000 or more — depending on your health, policy type, and market demand.

Advantages of Life Settlements

Potential Drawbacks to Consider

  • Immediate Cash Access:
    Useful for medical care, retirement income, or paying off debt.

  • Eliminate Premium Payments:
    You’ll no longer need to pay premiums once the policy is sold.

  • Higher Value Than Surrender:
    Often yields significantly more money than canceling your policy.

  • Flexible Use of Funds:
    No restrictions — you can use the money however you wish.

  • Tax Implications:
    Some or all of the settlement may be taxable. Consult a financial advisor.

  • Loss of Coverage:
    Once sold, your beneficiaries no longer receive the death benefit.

  • Privacy:
    Health and policy information is shared with potential buyers.

  • State Regulations:
    Not all states have identical life settlement laws — always work with licensed providers.

Real-Life Example

Case Study:
Mary, age 72, owned a $250,000 whole life policy. She had paid premiums for 20 years but no longer needed it since her children were financially secure.

  • Cash surrender value: $15,000

  • Life settlement offer: $62,000

Mary accepted the life settlement and used the proceeds to pay for home renovations and a new car. She also saved $3,500 per year in premiums.
Had she surrendered the policy, she would have received only $15,000 — losing out on $47,000.

How to Start the Life Settlement Process

  • Review Your Policy:
    Gather your policy statement, face amount, and premium schedule.

  • Get a Free Valuation:
    A licensed life settlement company or broker can estimate how much your policy is worth.

  • Compare Offers:
    Don’t accept the first bid — compare multiple offers for the best value.

  • Complete the Sale:
    Once you accept, ownership transfers to the buyer, and you receive your payment.

FREQUENTLY ASKED QUESTIONS (FAQ)

Yes, if it’s convertible to a permanent policy, it may qualify for a life settlement.

Typically, 10% to 40% of the death benefit, depending on your age, health, and policy details.

Yes, if you work with a licensed life settlement provider under your state’s Department of Insurance.

Part of it may be taxable as income or capital gains. Always consult a tax professional.

Most transactions close in 4–8 weeks, depending on paperwork and underwriting

Share:
Reading time: 4 min
Family - protected by universal life insurance

The need for life insurance depends on your individual circumstances, financial situation, and responsibilities. Here are some factors to consider when deciding if you need life insurance:

  1. Dependents: If you have dependents, such as a spouse, children, or aging parents, life insurance can provide financial security for them in the event of your death. It can help replace your income and cover their ongoing expenses, such as housing, education, and daily living costs.

  2. Debts: If you have outstanding debts like a mortgage, car loans, or credit card debt, life insurance can ensure that these debts are paid off if you pass away, preventing the burden from falling on your family.

  3. Financial goals: It can also be a tool for achieving long-term financial goals. It can provide funds for your children’s education, supplement your retirement savings, or leave a financial legacy to your beneficiaries.

  4. Co-signed loans or joint financial responsibilities: If you share financial obligations with someone else, such as a business partner or a co-signer on a loan, life insurance can protect them from shouldering the financial burden in case of your death.

  5. Estate planning: It can facilitate the transfer of assets and wealth to your heirs or beneficiaries, especially in cases where your estate might be subject to estate taxes.

  6. Peace of mind: It can provide peace of mind knowing that your loved ones will be financially secure if something were to happen to you.

On the other hand, if you’re single, have no dependents, no significant debts, and you have enough assets to cover your final expenses, you may not have an immediate need for life insurance. In this case, the decision to purchase life insurance might be driven by other factors like leaving a legacy or using it as an investment or tax planning tool.

Compare and Apply with Confidence

Finding affordable life insurance is now easier than ever. You can compare and apply for policies with terms of 10, 15, 20, 25, or 30 years.

  • Term Life Insurance – Affordable coverage for a set number of years.

  • Return of Premium (ROP) Term – Get back all your premiums at the end of the term (minus any loans).

For those considering lifelong protection, we also offer permanent life insurance options:

  • Whole Life Insurance – Lifetime coverage with guaranteed cash value growth.

  • Universal Life Insurance – Flexible lifetime coverage, with or without cash values.

Apply online or simply give us a call and we’ll help you design a plan that matches your goals and budget. Call 866.526.7264.

Compare for the Best Life Insurance Rates and Apply Online

Life insurance carriers
Share:
Reading time: 2 min
Grandfather and granddaughter

Building a Financial Legacy with Life Insurance: What You Need to Know

When people think about life insurance, they often focus solely on the death benefit—what it pays out when someone passes away. But in reality, life insurance is much more than a safety net; it’s a powerful tool for building a lasting financial legacy.

In this blog, we’ll explore how you can use life insurance not just to protect your family, but to create generational wealth and leave a meaningful legacy.

What Is a Financial Legacy?

A financial legacy refers to the wealth, assets, and financial wisdom you pass down to future generations. It’s not just about money—it’s about impact. A strong legacy can help your children, grandchildren, and even charitable causes thrive long after you’re gone.

The Role of Life Insurance in Legacy Planning

Life insurance plays a critical role in legacy planning because it offers tax-free benefits and liquidity when your loved ones need it most. Here’s how:

1. Tax-Free Death Benefit

Life insurance proceeds are generally not taxable, making them an efficient way to transfer wealth. This means your beneficiaries receive the full amount of the policy—without deductions.

2. Estate Planning Made Simple

Life insurance can cover estate taxes, funeral costs, and debts. This prevents your heirs from having to liquidate assets just to settle expenses.

3. Creating Generational Wealth

A permanent life insurance policy (like whole or universal life) can accumulate cash value over time. This value can be accessed during your lifetime, then passed on to future generations.

Types of Life Insurance for Legacy Building

Choosing the right policy is key. Here are the best options for legacy planning:

Whole Life Insurance
  • Fixed premiums

  • Guaranteed death benefit

  • Cash value accumulation

Universal Life Insurance
Term Life Insurance
  • Affordable and simple

  • Good for temporary needs

  • Can be converted to a permanent policy later

How to Maximize Your Legacy with Life Insurance

Start Early

The younger and healthier you are, the cheaper your premiums will be. Time is your best friend when building a financial legacy.

🔹 Name the Right Beneficiaries

Keep your policy up to date and be specific about who should receive the benefits. You can even designate a trust to manage the funds wisely.

🔹 Combine with Other Financial Tools

Life insurance should be part of a broader financial strategy that includes investments, wills, and retirement accounts.

Life Insurance Legacy Strategies

  • Use Insurance to Fund a Trust – Great for minors or dependents with special needs.

  • Gift Life Insurance to a Charity – Leave a philanthropic mark that reflects your values.

  • Equalize Inheritances – If you plan to leave a business or property to one child, insurance can provide equal value to others.

Final Thoughts

Your financial legacy is more than a number—it’s your story, your values, and your opportunity to shape the future. Life insurance gives you a practical and powerful way to do just that.

Whether you’re starting your legacy plan or updating it, now is the perfect time to explore how life insurance can help secure your family’s financial future.

FREQUENTLY ASKED QUESTIONS (FAQ)

Whole life insurance and universal life insurance are the most effective for legacy planning. They offer permanent coverage, guaranteed death benefits, and build cash value over time. These policies can be tailored to meet long-term goals and can even be used to fund trusts or charitable giving.

In most cases, life insurance death benefits are tax-free for beneficiaries. However, if the policy is part of a large estate, it may be subject to estate taxes. Proper planning with a financial advisor or estate planner can help minimize or avoid this.

Yes! You can name a charity as a beneficiary or donate an existing policy. This is a powerful way to support a cause you care about while leaving a lasting legacy of generosity.

Life insurance provides immediate liquidity upon your passing, which can help cover estate taxes, debts, and other costs. This prevents your family from having to sell off assets or property during a difficult time.

It depends on your financial goals, number of dependents, existing assets, and debts. A good rule of thumb is to aim for 10–15 times your annual income, but legacy planning may require more personalized strategies.

Yes. With permanent life insurance, you can borrow against or withdraw from the cash value for any purpose—college tuition, business funding, or even retirement income. Just keep in mind, it can reduce the death benefit if not repaid.

The earlier, the better. Premiums are lower when you’re younger and healthier, and your policy has more time to build value. Starting now helps ensure your legacy is secure no matter what the future holds.

Working with a licensed financial advisor or estate planner ensures that your life insurance and legacy plan align with your overall goals. They can help you navigate tax implications, choose the right policy, and structure your estate efficiently.

Share:
Reading time: 4 min
Family Protection

Best Term Life Insurance in 2025

Choosing the best term life insurance policy in 2025 involves evaluating your individual needs, such as age, health, budget, and financial goals. This guide breaks down key factors to consider and highlights top providers to help you make an informed decision.

Key Factors to Evaluate

  • Coverage Amount & Term Length
    Choose a policy that covers your family’s financial needs, such as mortgage, education, and living expenses. Common terms are 10, 20, or 30 years.

  • Premium Costs
    Ensure the premiums fit your budget, as you’ll need to pay them consistently.

  • Financial Strength of the Insurer
    Opt for companies with high ratings from agencies like AM Best, Moody’s, or Standard & Poor’s to ensure they can pay claims.

  • Riders & Additional Benefits
    Consider policies offering flexibility through riders like critical illness coverage, waiver of premium, or accidental death benefits.

  • Underwriting Process
    Decide if you prefer a policy that requires a medical exam or one that doesn’t (no-exam policies may have higher premiums).

How to Choose Term Life Insurance?

  • Compare Quotes: Use comparison independent websites like InsureInMinutes.com or SinglePremiumPlans.com.

  • Work with an Independent Agent: They can shop around for you.

  • Review Reviews & Ratings: Look at customer experiences and insurer reliability.

A few of the Top Term Life Insurance Providers in 2025

1. AIG (American International Group)

  • Why It’s Top:
    • Competitive rates, especially for higher coverage amounts.
    • Offers flexible term lengths (10 to 35 years).
    • Includes living benefits through their Quality of Life Insurance.
    • Financially stable with an A rating from AM Best.

2. Penn Mutual

  • Why It’s Top:
    • Focuses on customer satisfaction with personalized policies.
    • Highly flexible term life options with convertible features.
    • Strong financial ratings (A+ from AM Best) ensure long-term stability.
    • Offers accelerated underwriting for quicker approvals.

3. Pacific Life

  • Why It’s Top:
    • Known for high-net-worth policies and financial strength (A+ by AM Best).
    • Flexible term lengths and excellent term-to-permanent conversion options.
    • Offers robust riders, including child life insurance and accidental death benefits.

4. Banner Life (Legal & General)

  • Why It’s Top:
    • Offers some of the lowest term life insurance premiums in the market.
    • Flexible term lengths up to 40 years.
    • Generous underwriting policies, particularly for applicants with certain health conditions.
    • Financially strong with an A+ rating from AM Best.

5. Prudential

  • Why It’s Top:
    • Offers a wide range of riders, including living benefits for terminal illness.
    • Ideal for high coverage needs or applicants with unique situations, such as smokers.
    • Financially solid with an A+ rating from AM Best.
    • Flexible policy options and customizable coverage.

Conclusion

Selecting the best term life insurance in 2025 requires careful evaluation of your financial needs, policy options, and insurer reliability. AIG, Penn Mutual, Pacific Life, Banner Life, and Prudential stand out as top providers, offering flexible terms, robust coverage, and competitive premiums. Use comparison tools, consult independent agents, and review customer feedback to find a policy tailored to your goals.

For expert guidance or real-time quotes, contact us at 866.526.7264 today and secure your family’s financial future with confidence.

Share:
Reading time: 2 min

Affordability Matters

Term life insurance is perhaps the most sold life insurance plan in America. One of the biggest reasons is that term life offers you the highest death benefit for the lowest premium.

Limitations of Term Life Insurance

It covers you for only a specific period of time at a level premium and works like renting or leasing. Usually, the time spans are 10,15, 20, 25 and 30 years. A couple of companies have also introduced 35 and 40 years term (age and state restrictions apply). AIG offers a term plan which allows a applicant to select any number years between 10 and 35. If you happen to die within that time, your beneficiary will receive the life insurance proceeds federal income tax-free.

But if you live through that period, the premiums you paid for those years are gone.
To counter that disadvantage, a few life insurance companies offer a return of premium term life insurance options. These plans cost you more, but at the end of the term, you get a refund of all the premiums you paid, minus any loans. No matter which type of term life insurance you take, at the end of the term you have no coverage on yourself.

Renewable Term Life Insurance

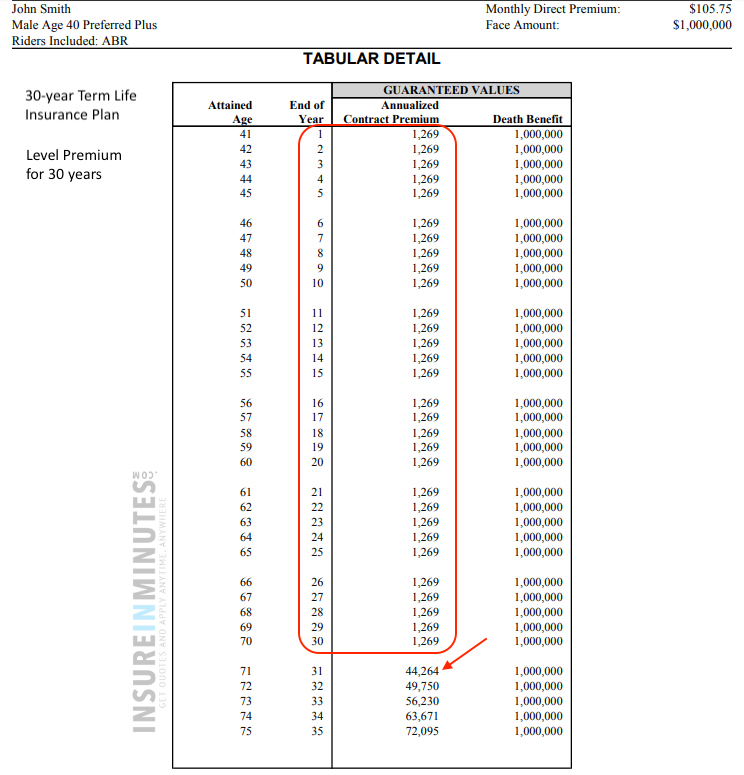
Now, most term life insurance plans are annually renewable at the end of the term. However, it is financially impossible for most people to maintain a term life policy after the term ends. The rates are exorbitantly high. For example, a 40 years old male can pay as little as $105.75 per month or $1,269 annually for a 30-year term insurance for a $1000,000 coverage. At the end of 30 years, if he wants to renew his policy, his premium jumps from $1,269 to $44,264 per year. Also, the premium keeps increasing every year thereafter. So renewability of a term insurance policy is really a joke. Refer to this image below for details.

Term Life Insurance Illustration

For some people, this product works like a charm. It protects the family’s ability to keep on paying the mortgage on the house or any other loan in case of sudden death of the income provider. It also provides much needed financial protection to the family when children are growing up. Basically, term life insurance works well when you want to cover temporary financial obligations.

For those who are looking for a longer term of coverage guaranteed universal life insurance is the best option.

LIFE INSURANCE QUOTES

Financial Heaven or Hell

I recently met someone who purchased a $1M, 20-year term life insurance with a thought that after twenty years he will not need any kind of life insurance because he will by that time make it financially. The guy is a 42-year old realtor and is not my client. I really hope and wish that everything works out for him the way he has planned his finances. BUT…what in case they don’t!

He has a mortgage, a young 11-year old daughter, and a non-working wife.

What if his wife outlives him by 10 years much later in life when he has no life insurance on him? If his financial gains are strong and the income is going to continue even after when he is gone, the spouse will do just fine. Otherwise, she will have to go through a financial hell that the realtor has not anticipated.

In the last 20 years, I have talked to a number of people who bought term life when they were young and later in life wanted permanent coverage that could last until the end of life. The only reason they bought term life insurance was because it was the least expensive option.

By the time, they come to this realization; many of them cannot afford to buy a permanent life insurance plan (coverage beyond age 100) or end up paying very high premiums. Your premium at this stage is based on your current age and health. The older you are, the higher you pay, even if you are in good health.

Options to Convert Term Life Insurance

Most term life insurance plans come with an option to convert the entire or partial amount of death benefit to a permanent life insurance plan (coverage beyond age 100). The time period within which you can convert depends on what the carrier offers.

The biggest advantage of conversion is that the insured doesn’t have to go through a medical exam to qualify. You may have any number of illnesses or diseases but you cannot be clinically disabled. Just agree to pay your new premium and you are set. Also, you can mostly convert the entire term policy or part of the policy into a permanent plan.
The biggest disadvantage is that the longer you wait to convert, the higher you pay.

I always suggest my clients to layer their life insurance plans, depending on what they can afford and what their needs are today and also their anticipated needs in the future.

It is important to mention that one can have multiple life insurance policies to take care of various kinds of needs in life.

Share:
Reading time: 4 min

Single-premium guaranteed universal life (SPGUL) insurance is a type of life insurance where you make one large payment upfront, and the insurance guarantees a death benefit for your entire life, regardless of how the cash value in the policy performs. It can be considered a financial legacy life insurance plan.

Here’s how it works:

  • One-Time Payment: You make a single lump-sum payment, and in return, you’re covered for life without needing to make any more payments.
  • Guaranteed Death Benefit: The insurance company guarantees that your beneficiaries will receive a set amount (the death benefit) when you pass away, no matter what happens to the policy’s cash value.
  • Limited Cash Value Growth: Unlike other policies, the cash value in SPGUL usually doesn’t grow much. The focus is more on the guaranteed death benefit, so the cash value isn’t as important here.

Example of Single Premium Life Insurance

Let’s say you’re 55 years old and decide to buy a single-premium guaranteed universal life insurance policy. You pay $100,000 upfront. The policy guarantees that, no matter what happens, when you pass away, your family will receive a death benefit of $300,000. Even if the policy’s cash value doesn’t grow or decline over time, the $300,000 death benefit is still guaranteed.

If you want to get an instant quote for a single premium guaranteed universal life insurance plan, click here. If you’re going to discuss it with a licensed professional, call us at 866.526.7264. We will be glad to hear from you.

This type of policy is great for people who want the certainty of a fixed death benefit with no future payments, but it’s not ideal if you’re looking to build significant cash value.

FREQUENTLY ASKED QUESTIONS (FAQ)

If you want both a guaranteed death benefit and cash value growth, you might want to consider a regular single-premium universal life (SPUL), or a participating single-premium whole life (SPWL) insurance policy instead of the single-premium guaranteed universal life (SPGUL) policy. Here’s why:

  • Single-Premium Universal Life (SPUL) and Single-Premium Whole Life (SPWL): These policies provide a death benefit, but it also allows your cash value to grow over time. The growth is based on the interest rates set by the insurance company or linked to certain investments, or dividends. You can borrow against or withdraw from this cash value if you need money in the future.

  • Cash Value Growth: With SPUL or SPWL, your policy builds up a cash value, which can grow over time. While  in SPUL, the death benefit is not always guaranteed at the same level (because it may depend on the performance of the cash value), this policy gives you more flexibility if you want to access that money during your lifetime. In SPWL, the death benefit not only stays guaranteed but may also increase over the years.

Single-premium guaranteed universal life (SPGUL) insurance has its advantages, such as lifelong coverage with no need for ongoing payments, but it also comes with several disadvantages. Here are the key drawbacks:

1. High Initial Cost

  • Disadvantage: You have to make one large, upfront payment. This can be a significant burden for those without substantial liquid assets.
  • Example: If the premium is $100,000, you must have that amount available immediately, which could limit your financial flexibility.

2. Limited or No Cash Value Growth

  • Disadvantage: SPGUL policies typically do not focus on building cash value. While you get a guaranteed death benefit, there’s little to no accumulation of cash value that you can borrow or withdraw from during your life.
  • Example: Unlike other types of life insurance where you can tap into the cash value, SPGUL policies usually don’t provide significant funds for emergencies or other needs.

3. Lack of Flexibility

  • Disadvantage: Once the premium is paid, you can’t modify the policy or reduce the death benefit to lower costs. It’s a “set it and forget it” type of policy.
  • Example: If your financial situation changes and you need cash, or if you no longer need as much life insurance, you can’t adjust the policy or recoup part of the premium.

4. No Potential for Policy Growth

  • Disadvantage: SPGUL policies are designed to provide a guaranteed death benefit, but they don’t benefit from market growth or higher interest rates like some other policies.
  • Example: In a regular universal life policy, the cash value could grow with the market. With SPGUL, there’s no opportunity for the policy’s value to increase beyond the guaranteed death benefit.

5. Modified Endowment Contract (MEC) Risks

  • Disadvantage: SPGUL policies are often classified as Modified Endowment Contracts (MECs), which can change how withdrawals and loans from the policy are taxed. Any withdrawals or loans could be subject to regular income tax and a 10% penalty if taken before age 59 ½.
  • Example: If you withdraw funds from the policy’s limited cash value, you might face tax penalties, unlike other life insurance policies that allow for more tax-favored withdrawals.

6. Missed Investment Opportunities

  • Disadvantage: Because SPGUL policies don’t accumulate much cash value, the large sum you pay upfront could be better invested elsewhere. By locking the money into an insurance policy, you miss the potential for higher returns through other investment vehicles.
  • Example: Instead of paying $50,000 into an SPGUL policy, you might be able to invest in the stock market or real estate, which could potentially yield higher returns over time.

7. Limited Death Benefit for Large Premiums

  • Disadvantage: Compared to other types of life insurance, the death benefit you receive for the premium you pay may be lower. SPGUL focuses on guaranteeing a death benefit but may not provide as much coverage as other types of policies where payments are spread over time.
  • Example: A $100,000 single premium might only provide a $250,000 death benefit, while a different type of policy could offer a higher death benefit for a similar total premium paid over several years.

8. Loss of Liquidity

  • Disadvantage: Once you make the single payment, you lose access to that lump sum. If an emergency arises or you need access to those funds for another purpose, the money is tied up in the policy, and there’s no easy way to retrieve it without canceling the policy.
  • Example: If you face a medical emergency and need immediate cash, the large sum you put into the SPGUL policy won’t be accessible for such needs.

9. Penalties for Policy Surrender

  • Disadvantage: If you decide to surrender the policy early, you might not get back the full amount you paid. The insurance company may charge surrender fees, especially in the first several years.
  • Example: If you pay $100,000 upfront and decide to cancel after five years, you may only receive a portion of your original payment due to surrender charges.

In Summary:

While SPGUL policies offer a guaranteed death benefit and the simplicity of one payment, the lack of cash value growth, high upfront costs, and limited flexibility can be significant drawbacks. This type of policy works best for those who want guaranteed life insurance protection and can afford to make a large payment without needing the funds for other purposes or investments.

Single-premium whole life insurance has its benefits, such as lifelong coverage and cash value growth, but it also comes with several disadvantages. Here are the key drawbacks:

1. High Upfront Cost

  • Disadvantage: You have to make one large, lump-sum payment to fund the policy, which can be financially challenging for many people.
  • Example: If you want a significant death benefit, the single premium could be tens or hundreds of thousands of dollars, tying up a large amount of money upfront.

2. Limited Liquidity

  • Disadvantage: While single-premium whole life policies build cash value, it can take several years before the cash value grows significantly enough to access. Early withdrawals or loans may reduce the death benefit.
  • Example: If you pay $100,000 upfront, you might not be able to access a substantial portion of the cash value for years, limiting its use in emergencies.

3. Tax Implications (MEC Status)

  • Disadvantage: Single-premium whole life policies are often classified as Modified Endowment Contracts (MECs), meaning any loans or withdrawals from the cash value are taxed as regular income, and if taken before age 59 ½, they may be subject to an additional 10% tax penalty.
  • Example: If you take out $10,000 from your cash value and are under 59 ½, you could face a tax bill and a 10% penalty, making it costly to access your money.

4. Opportunity Cost

  • Disadvantage: The large upfront payment could be invested elsewhere, potentially yielding higher returns. By locking it into a single-premium whole life policy, you may miss out on other investment opportunities.
  • Example: Instead of putting $100,000 into a life insurance policy, you could invest it in the stock market or real estate, which may offer better long-term growth depending on market conditions.

5. Limited Flexibility

  • Disadvantage: Once the premium is paid, you can’t reduce or increase the death benefit or make changes to the policy without penalties or consequences. If your financial situation changes, you can’t adjust the policy to meet your new needs.
  • Example: If you find yourself needing less life insurance in the future, you can’t reduce the death benefit or reclaim part of the premium.

6. Lower Death Benefit Compared to Traditional Policies

  • Disadvantage: The death benefit for single-premium whole life policies may be lower than that of traditional life insurance policies where you make regular payments over time.
  • Example: A single premium of $50,000 might give you a death benefit of $150,000, while paying premiums over time for the same amount could potentially provide a higher death benefit.

7. Policy Lapses If Loans Aren’t Repaid

  • Disadvantage: If you borrow from the cash value and don’t repay the loan, the policy’s death benefit could be reduced or even cause the policy to lapse.
  • Example: If you borrow $20,000 from the cash value but don’t repay it, the death benefit may be reduced by the loan amount plus interest, potentially leaving less for your beneficiaries.

8. Surrender Charges

  • Disadvantage: If you decide to surrender the policy within the first several years, there may be surrender charges that reduce the amount of money you get back.
  • Example: If you pay $100,000 and surrender the policy after 5 years, you might only get back $90,000 due to surrender charges.

9. Slow Cash Value Growth

  • Disadvantage: While single-premium whole life policies do build cash value, the growth is often slower in the early years compared to other investment options, especially if interest rates are low.
  • Example: It may take 10 or more years before the cash value grows significantly beyond your initial premium payment.

10. Inflation Risk

  • Disadvantage: The fixed death benefit does not account for inflation. Over time, the purchasing power of the death benefit could decrease, which means the payout may not provide the same level of financial support to your beneficiaries in the future.
  • Example: A $200,000 death benefit might be sufficient today but may not cover the same expenses in 20 or 30 years due to inflation.

In Summary:

The primary disadvantages of single-premium whole life insurance include the high initial cost, limited liquidity, and tax implications of accessing the cash value. Additionally, you may miss out on other investment opportunities, and the death benefit might be lower than what you’d get with regular premium policies. For those who prioritize cash value growth and flexibility, this policy might not be the best fit.

Share:
Reading time: 9 min
Limited Pay Life Insurance

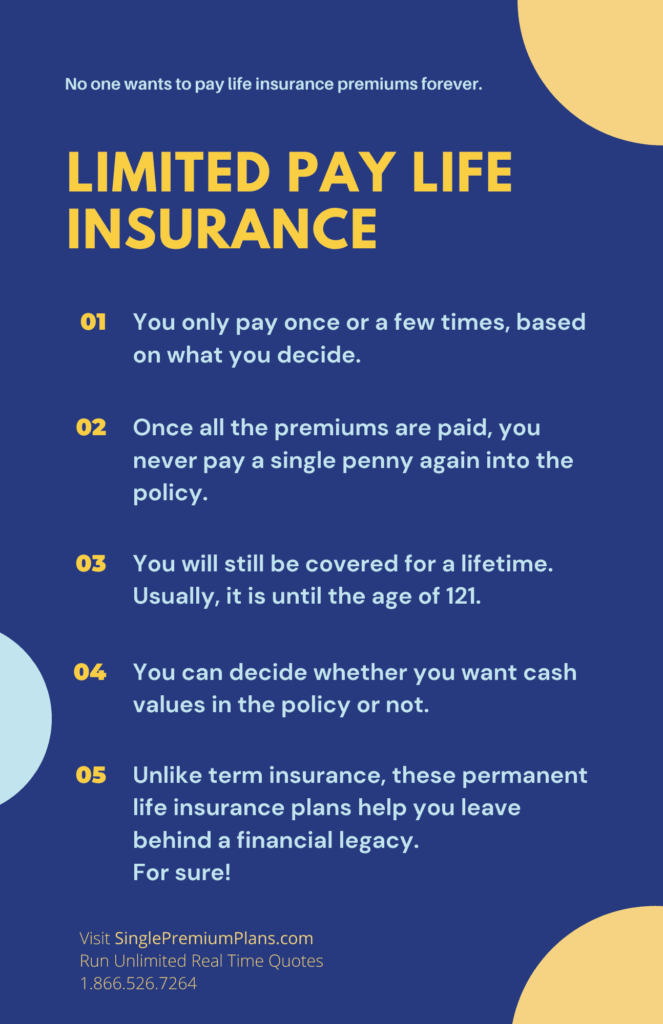
By now, I must have talked to a few thousand people looking into life insurance to protect their loved ones. I have not met a single person who wants to pay a premium forever. Whether it is a car, a house, or a life insurance policy, as soon as you are done paying the final premium, there is a special kind of relief as if a pall of freedom just dawned over your life.

What is Limited Pay Life Insurance?

Most of these plans are either universal life or whole life insurance plans. Both are custom-designed to suit what the client wants. You can choose to pay a single premium for your life insurance policy or spread the payments over the years.

A couple of years back, a 34 years old female in good health came to me through a referral. She had a guaranteed universal life insurance plan that covered her until the age of 121. She was paying about $90 per month to keep that policy. She was glad about the fact that unlike a 30 years term insurance, her policy will keep her covered for entire life. So I asked her, “Are you comfortable with the fact that you will pay your premium until age 100.” “I wish I don’t have to,” was her answer. Very logical and reasonable.

Long story short, since she purchased that policy only in the last one year, I managed to find her the best class premium from an A+ rated carrier and she agreed to pay a premium of $125 monthly only until the age of 65. After that, the guaranteed universal life policy would continue until the age of 121. Not a single extra premium had to be paid after age 65. In my experience, most people would like to have something like that if they can afford it. Nobody wants premium on a life insurance policy forever.

Limited Pay Life Insurance

Single Pay Term Life Insurance

A handful of life insurance companies offer their customers to pay a single premium on a term life insurance plan. By choosing this option, you can end up saving up to 33% on the total premium of a 10, 15, 20, or 30 years term policy.

If you want a personalized quote on single premium term plan, give us a call at 1 866 526 7264.

Single Pay Universal Life Insurance

Most of these plans are guaranteed universal life plans with almost to no cash values. Their biggest benefit is:
• that you will never pay another premium, and
• your loved one will have the financial protection from your life insurance policy as long as you live.
(I am assuming that no one lives all the way to 121).

Single Premium Life Insurance

Single Pay Whole Life Insurance

Most of these plans are participating or non-participating plans with cash values. Their biggest benefit is:
• that you will never pay another premium, and
• your loved one will have the financial protection from your life insurance policy as long as you live.
• that if you have a participating whole life plan, your death benefit or face amount of the policy will also increase over time. That works as a kind of inflation protection.
• that you can borrow loans from your own cash values in the policy and pay back with time.
• that this method of self-financing can be successfully used of you start with a whole life plan early in life.

What is Modified Endowment Contract (MEC)?

A simple explanation is that is it an overfunded life insurance policy. The only time MEC makes a difference is when you have large cash values in the policy. Without those MEC is inconsequential.
A modified endowment contract gets the same treatment as a non-qualified annuity contract.
Income tax

How to Avoid a MEC?

• Make limited premiums into the policy for few years ( 7 years and above).
• If you want to get a single premium whole life insurance, make sure that the company offers a premium deposit fund.

“It is an account that allows you to pre-pay policy premiums with one lump sum, without causing the policy to be a Modified Endowment Contract (MEC). This allows your policy to keep the favorable tax treatment provided by life insurance while earning a competitive interest rate.
Each year, the specified annual premium is automatically transferred from this account to your life insurance policy. This is a convenient and systematic way to fund your policy, while providing you with peace of mind.” (source: Penn Mutual)

BOTTOMLINE
It's peace of mind for a lifetime.

Limited pay life insurance plans are simply custom designed plans that allow you to pay your premiums for as long as you want to pay into the policy while making sure that the policy remain active for whatever number of years you choose. Usually, guaranteed universal life and whole life insurance plans offer coverage until the age of 121.

Life insurance carriers 
Single Premium Life Insurance

Share:
Reading time: 4 min
Seniors looking for final expense insurance.

Everything You Need to Know About Final Expense Life Insurance

Are you worried about leaving your loved ones with a financial burden after you pass away? Final expense life insurance with no waiting period could be the solution you’ve been looking for. Depending upon what you qualify for, these plans may or may not have a waiting period.

What is Final Expense Life Insurance?

Final expense life insurance is a type of insurance coverage specifically designed to cover the expenses associated with your death, such as funeral costs, medical bills, and other end-of-life expenses. It provides your loved ones with a lump sum payout that can help alleviate the financial burden during an already difficult time.

Unlike traditional life insurance policies, final expense life insurance is typically more affordable and easier to qualify for. It is also known as burial insurance or funeral insurance, as it is specifically intended to cover the costs associated with your final arrangements.

Understanding the Waiting Period

Black senior citizen

One of the key features of final expense life insurance is the waiting period. It is a time that must pass after you purchase the policy before your coverage becomes fully active. During this waiting period, if you were to pass away, the policy may only provide a partial payout or refund of premiums paid, rather than the full death benefit.

The length of the waiting period varies depending on the insurance company and the specific policy. It can range from a few months to a couple of years. However, with final expense life insurance with no waiting period, your coverage starts immediately after you sign up, ensuring that your loved ones are fully protected from day one.

The reason for a waiting period is usually the severe condition of the insured’s health. 

Monetarily speaking, the insurance company wants to make sure that it has collected a few premiums before it has to pay a high face amount if the insured passes away within the first two or three years.

Final expense insurance | No waiting period

This option offers several benefits that make it an attractive option for individuals looking to protect their loved ones from the financial burden of final expenses.

1. Immediate Protection: With no waiting period, your coverage begins as soon as you sign up for the policy. This means that your loved ones will receive the full death benefit in the event of your passing, providing them with immediate financial support during a challenging time.

2. Affordable Premiums: Final expense life insurance policies with no waiting period often come with affordable premium rates. This makes it accessible for individuals who may have difficulty qualifying for traditional life insurance due to age or health conditions.

3. Flexible Coverage Options: These types of policies typically offer flexible coverage options, allowing you to choose a death benefit amount that suits your needs. You can tailor your coverage to ensure that your funeral expenses, outstanding medical bills, and other end-of-life costs are adequately covered.

4. Tax-Free Payout: The death benefit of final expense life insurance is generally tax-free. This means that your loved ones will receive the full payout without having to pay income taxes on the amount received.

Final expense life insurance with no waiting period

Final expense life insurance with no waiting period is designed to be accessible for individuals who may have difficulty qualifying for traditional life insurance policies. Here are some key factors to consider when determining your eligibility for this type of coverage:

1. Age: Final expense life insurance is typically available for individuals between the ages of 50 and 85. Some insurance companies may offer coverage to individuals outside this age range, so it’s worth exploring your options.

2. Health Condition: Final expense life insurance policies with no waiting period often have simplified underwriting, meaning they do not require a medical exam or extensive health questionnaires. This makes it easier for individuals with pre-existing health conditions to qualify for coverage.

3. Tobacco Use: While tobacco use may affect your premium rates, it does not necessarily disqualify you from obtaining final expense life insurance with no waiting period. Some insurance companies may offer coverage at higher rates for smokers.

4. Coverage Amount: The death benefit amount you choose may impact your eligibility for final expense life insurance with no waiting period. Some insurance companies have maximum coverage limits, so it’s important to consider your desired coverage amount when exploring your options.

Share:
Reading time: 3 min
Page 1 of 3123